

© Wild Oats Publishing 2026
Wild Oats Grain Market Advisory

Site Created August 15, 1996; Last Updated November 03, 2026
Web site created by Branscombe Consulting
Wild Oats is published 40 times per year by Wild Oats Publishing, 905 - 167 Lombard Avenue,
Winnipeg R3B 0V3. Tel. (204) 942-1459 Fax (204) 942-7652 E-mail: wildoats@canadagrain.com
Information is secured from sources believed reliable, but 100% accuracy cannot be guaranteed.
Persons associated with Wild Oats deal commercially with businesses active in Prairie grain markets
and may hold positions on their own accounts in commodities discussed herein. ISSN 1185-2194
Copyright 2025. All rights reserved. The Wild Oats Grain Market Advisory is protected by copyright.
Copying, retransmission or redistribution, in whole or in part, without the prior written approval of Wild
Oats Publishing is strictly prohibited.


Manitoba Farmgate Prices
Prices are FOB farm, unless noted otherwise, as of November 03, 2026. Your local rate may differ.
Basis
Net
Per Bushel
Canola: Prices under Jan at $782; 2027/28 under Nov27 at $774
Del Elevator
29 - 54
728 - 753
16.51 - 17.08
Fall 2027-28
54 - 61
712 - 720
16.16 - 16.33
Barley
Feed Del Elevator
218 - 237
4.75 - 5.15
FOB Farm
223 - 230
4.85 - 5.00
New Crop 2027-28: not quoted
Malt Del Elevator
247 - 264
5.37 - 5.75
Wheat
Feed Del Elevator
248 - 254
6.75 - 6.91
FOB Farm
239
6.50
Milling Wheat (Del)
CWRS #1
286 - 302
7.78 - 8.21
New Crop 2027-28
255 - 275
6.94 - 7.48
CWRW #2 (Del)
268
7.28
Flax
$16.00 - 17.07 del
Oats
$3.50 - 4.25; $3.68 - 4.59 del
Corn
$4.85 - 5.26 del
Rye
$4.05 - 6.75 del
Soybeans
$14.82 - 15.60 del; Fall 2027: $12.65 - 13.03 del
Lentils
Laird (Del) #1: 27.5 - 32¢; #2: 27.5 - 32¢; X3: 19 - 26.5¢; #3: 16 - 23.5¢
Eston (Del): #1: 18.5 - 28¢; #2: 17.5 - 23¢; X3: 14 - 18¢; #3: 12.5 - 16¢
Richlea (Del): #1: 18.5 - 29¢; #2: 17.5 - 29¢; X3: 14.5 - 15.5¢; #3: 12.5 - 13.5¢
Crimson (Del): #2+: 23 - 25¢; X3: 19 - 21.5¢; #3: 18 - 18.5¢
Canary Seed
20 - 21¢; 19.75 - 20.5¢ del
Peas
Green: $7.50 - 9.50 del Sk
Yellow: $8.38 - 9.75 del Sk
Feed: $9.00 del
Mustard (Del Sk)
Yellow: 39 - 41¢
Brown: 36 - 38¢
Oriental: 36 - 38¢
Dry Edible Beans (del)
Pinto: 44¢; Navy: 47.75¢; Black: 45.75¢; Great Northern: 43¢
Delivered North Dakota Plant/Elevator - $US/bu [$CND/bu in brackets]
DNS [14%]: $5.29 - 6.14 [$7.40 - 8.58]; Durum: $6.00 - 6.75 [$8.39 - 9.44]
Flax: $12.00 - 14.00 [$16.78 - 19.57]; Canola: $11.08 - 12.80 [$15.48 - 16.06]
Soybeans: $11.00 - 11.49 [$15.38 - 16.06]; Corn: $3.37 - 3.62 [$4.71 - 5.06]
Barley Feed: $2.90 - 3.00 [$4.05 - 4.19]; Oats: $2.10 - 2.68 [$2.94 - 3.72]
Sunflower Oil: 23 - 25.7¢ [32.2 - 35.9¢]; NuSun: 20.0¢ [28¢]
Peas: Yellow: $4.75 - 7.50 [$6.64 - 10.49]; Green: $6.50 - 7.50 [$9.08 - 10.49]
Pinto: 42 - 43.0¢ [58.7 - 60.1¢]; Navy: 38 - 40¢ [53.1 - 55.9¢]
Black: 40.0 - 45.0¢ [55.9 - 62.9¢]; Kidney Light Red: 47.0¢ [65.7¢]
Kidney Dark Red: 38.0¢ [53.1¢]; Great Northern: 40.0¢ [55.9¢]
Saskatchewan Farmgate Prices
Prices are FOB farm, unless noted otherwise, as of November 03, 2026. Your local rate may differ.
Basis
Net
Per Bushel
Canola: Prices under Jan at $782; 2027/28 under Nov27 at $774
Del Elevator
39 - 74
708 - 743
16.06 - 16.85
New Crop 2027-28
20 - 93
681 - 754
15.45 - 17.10
Nexera: $19.05 Jan; $19.19 (Mar); $18.98 (Sep-Oct 2027)
Barley
Feed Del Elevator
195 - 237
4.24 - 5.15
FOB Farm
223 - 239
4.85 - 5.20
New Crop 2027-28 not quoted
Malt (Del)
269 - 283
5.85 - 6.17
Wheat
Feed Del Elevator
292
7.95
FOB Farm not quoted
New Crop 2027-28 not quoted
Milling (Del)
CWRS #1
279 - 298
7.60 - 8.10
New Crop 2027-28
248 - 256
6.75 - 6.96
CPRS #1
223 - 249
6.35 - 6.78
Durum (Del)
297 - 301
8.07 - 8.19
FOB Farm
327 - 349
8.90 - 9.50
Flax: $15.47 - 15.63 del; Brown $17.00 - 18.00 del
Oats: Feed: $2.00 - 2.45; Milling: $2.64 - 4.50 del; #2 $3.50 - 4.25 Fob Farm
Rye: 2CW: $3.78 - 4.55 del; Fall 2027: $4.33 - 4.55
Soybeans
$15.40 - 15.80; $15.76 del; Fall 2027: $13.54 - 13.92 del
Lentils
Laird #1: 27.5 - 32¢ del; #2: 28 - 30¢; 27.5 - 32¢ del
X3: 21 - 23¢; 19 - 26.5¢ del; #3: 19 - 20¢; 16 - 23.5¢ del
Eston: #1: 27 - 28¢; 18.5 - 28¢ del; #2: 18 - 20¢; 17.5 - 23¢ del
X3: 17 - 18¢; 14 - 18¢ del; #3: 14 - 16¢; 12.5 - 16¢ del
Richlea: #1: 16 - 17¢; 18.5 - 29¢ del; #2: 17.5 - 29¢ del; X3: 14.5 - 15.5¢ del
#3: 12.5 - 13.5¢ del
Crimson: #2+: 23 - 24¢; 23 - 25¢ del; X3: 18 - 19¢; 19 - 21.5¢ del
#3: 16 - 17¢; 18 - 18.5¢ del
Canary Seed
20 - 21¢; 19.75 - 20.5¢ del
Peas
Green: $8.50 - 9.00; $7.50 - 9.50 del
Yellow: $8.00 - 9.00; $8.38 - 9.75 del
Feed Peas: $5.95 - 7.00 del
Chickpeas
Kabuli (del): 10mm: 31 - 32¢; 9mm: 29.75 - 30¢; 8mm: 25.75 - 26¢
Desi (del): 26 - 30¢
Mustard
Yellow: 38 - 40¢; 39 - 41¢ del
Brown: 36 - 38¢; 36 - 38¢ del
Oriental: 37 - 38¢; 36 - 38¢ del
Alberta Farmgate Prices
Prices are FOB farm, unless noted otherwise, as of November 03, 2026. Your local rate may differ.
Basis
Net
Per Bushel
Canola: Prices under Nov at $782; 2027/28 under Nov27 at $774
Del Elevator
47 - 62
720 - 735
16.32 - 16.66
2027-28
58 - 82
692 - 715
15.70 - 16.23
Barley
Feed Del Elevator
239 - 300
5.05 - 6.53
Lethbridge
290 - 300
6.31 - 6.53
Vermillion
271 - 290
5.90 - 6.31
Rycroft
243 - 264
5.29 - 5.75
FOB Farm
241 - 255
5.25 - 5.55
New Crop 2027-28 not quoted
Malt: not quoted
Wheat
Feed Del Elevator
234 - 315
6.38 - 8.56
Lethbridge
295 - 315
8.03 - 8.57
Red Deer
308 - 315
8.38 - 8.56
Viking not quoted
New Crop 2027-28 not quoted
Milling (Del)
CWRS #1
293 - 307
7.97 - 8.34
New Crop 2027-28
265 - 266
7.20 - 7.25
CPRS #2
252 - 258
6.85 - 7.01
New Crop 2027-28 not quoted
Durum
300 - 321
8.17 - 8.75
New Crop 2027-28 not quoted
Oats
Del Elevator
259 - 300
3.99 - 4.63
Viking not quoted
Edmonton
259 - 300
3.99 - 4.63
Flax
$16.30 del
Corn
$7.42 - 7.94 del
Lentils
Laird (Del) #1: 27.5 - 32¢; #2: 27.5 - 32¢; X3: 19 - 26.5¢; #3: 16 - 23.5¢
Eston (Del): #1: 18.5 - 28¢; #2: 17.5 - 23¢; X3: 14 - 18¢; #3: 12.5 - 16¢
Richlea (Del): #1: 18.5 - 29¢; #2: 17.5 - 29¢; X3: 14.5 - 15.5¢; #3: 12.5 - 13.5¢
Crimson (Del): #2+: 23 - 25¢; X3: 19 - 21.5¢; #3: 18 - 18.5¢
Canary Seed
20 - 21¢; 19.75 - 20.5¢ del
Peas
Green: $7.50 - 9.50 del Sk
Yellow: $8.38 - 9.75 del Sk
Feed: $9.00 del
Mustard (Del Sk)
Yellow: 39 - 41¢
Brown: 36 - 38¢
Oriental: 36 - 38¢
Dry Edible Beans (del)
Pinto: 44¢; Navy: 47.75¢; Black: 45.75¢; Great Northern: 43¢
Delivered Montana Elevator - $US/bu [$CND/bu in brackets ]
DNS [14%]: $4.85 - 5.85 [$6.78 - 8.18]; Durum: $5.50 - 6.00 [$7.69 - 8.39]
HRW [13%]: $4.47 - 5.69 [$6.25 - 7.95]
Barley: Feed: $3.64 [$5.09]; Malt: not quoted

From the Floor
Opinion derived from traders
We take for granted the fact that, when we own land, we have clear title (assuming, of course, there’s no
inter-family issue).
How farmers in Zimbabwe would love that! Now there’s a complicated ownership system. About 25 years
ago, Robert Mugabe, the liberation hero-turned-dictator, dispatched thugs to grab mostly white-owned
farms. The land went to about 150,000 households, each given 15 acres, in theory enough to establish a
viable farm.
Few of these “farmers” actually made it. Most however, or their children, still hold nominal title and lend
their land to a larger joint venture in return for a share of the revenue.
Financing is the big problem. Banks are reluctant to take disputed-ownership land as collateral for
operating money. Most farms grow tobacco for Chinese cigarette manufacturers. They front the necessary
funds and take delivery at harvest.
Street Smart - Rhett Montgomery
With the rapid expansion in global crush due to the biofuel boom, the U.S. is not as reliant on export
demand.
Rhett Montgomery, a DTN analyst, on increased soybean use for biofuel.


Futures Soggy
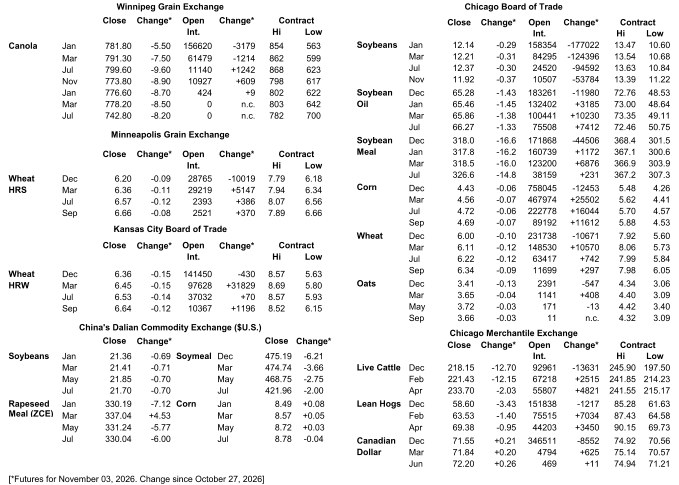
Most grain and oilseed futures are in deep slumps. Canola has
lost $45/t since mid-October. Corn has lost 80 cents/bu since
late September, Minneapolis wheat lost about $1.70/bu since
early October, soybeans down $1.30/bu since early August.
Fundamentals are not terrible but funds are selling futures and
farmers are selling physical.
Seasonals suggest contract lows in late October/early
November, then rising into January.
INTERNET EDITION
Volume 37 Number 11
November 03, 2026
Re-broadcast, re-distribution and/or forwarding of the Wild Oats Grain Market Advisory, including
internally within offices and organizations, is prohibited.
Mustard Quiet - John Duvenaud
There was a decent mustard crop this year -
158,000 tonnes, according to AgCanada.
Yellow yields averaged around 20 bu/ac, brown 18 -
20 bu/ac and Oriental 22 bu/ac. All that heat in July
took the top off yield potential. There are few mustard
growers with bin space issues.
The size of the carryover has been an issue since
2024. That year we grew a bin-busting 288,000
tonnes of mustard. The carryout was 143,000 tonnes
which is enough to satisfy a year of normal domestic
use plus exports. We've cut back on plantings but
yields remain strong and the carryout is projected at a
hefty 170,000 tonnes next July.
Trade is slow. Few end users are actively reaching
for mustard and there is little action from farmers
wanting to move mustard. Importers are looking at
ample Canadian stocks and putting sourcing on the
back burner.
There is still active trade. Consumers continue to
eat mustard and manufacturers continue to supply it.
It's just that there is no urgency to buy.
Yellow trades around 40 cents/lb, brown 37¢ - 38¢
and Oriental also 37¢ - 38¢. If those numbers work for
you, there's nothing wrong with cashing in a few
bushels. Nor, however, is there any urgency.
The carryover isn't as bad as it appears at first
glance. Maybe 50,000 to 80,000 tonnes are off-grade,
too dark yellow and brown. That mustard does have
some value but most manufacturers won't touch it.
That makes the fundamentals considerably more
friendly.
Watch the markets this winter. If prices are going to
move higher we may not know until Crop Production
in January. In the meantime fundamentals aren't that
bad, consumers are still eating mustard and trade is
ongoing.
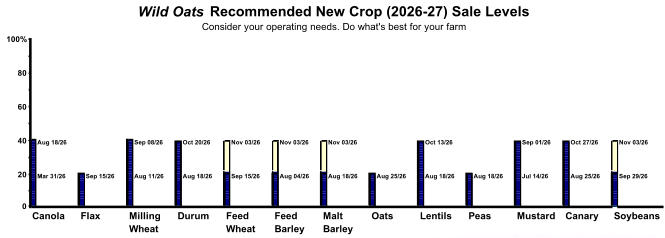
Wild Oats is already 40% sold on 2026 mustard.
Keep your powder dry for the time-being.
Sell Soybeans
Nov soybean futures have been falling since mid-
September, from US$13.35/bu to close at $12.03
today. American soybean harvest is at 88% and
USDA forecasts record production of 4.56 mln
bushels. South American seeding is proceeding
apace, with Argentina a quarter planted and Brazil
about half done. South America has a few weather
issues but conditions are favourable.
Funds continue with their liquidation of a record
large long position in soybean futures although they
are still long 176,000 soybean contracts. Crude oil
lost $8/barrel yesterday (Monday) on rumours that the
US/Iranian war was winding down. Frankly, that looks
more like market manipulation than conflict resolution,
but who knows?
In any case, American soybean production was a
record, production prospects in South America look
good and the price trend is down. Manitoba elevators
are still paying $15.05 - $15.30/bu and taking delivery
(put in a target of $15.50).
Sell the second 20% increment of your 2026
soybeans bringing sales to 40%. Yes, current bids are
well under off-combine prices but they may well be
above those available a month from now.
Wheat supplies in 2025, at 37.2 mmt, were a
record. Our biggest buyers were Indonesia (11%),
China (10%), Japan (9%) and Bangladesh (6%).
The 2026 crop was down 4%. Quality is below
average at 77% 1 and 2CWRS. Protein is 13.9%,
about average.
Barley supplies in 2025 rose by 18% but
exports were strong with China taking 60%.
Production in 2026 was the same as in 2025 on
bigger seedings but lower yields.
Oat supplies grew strongly in 2025. Oat
production this year is down sharply and there are
serious quality issues. Rye supplies in 2025
were the highest in decades. Exports were up,
almost all to USA.
Canola had record production in 2025, 22%
above average. The domestic crush rose 13% on
a record crush of 12.9 mmt.
Flax production was quite strong in 2025, 18%
above average. Exports were strong with the
biggest markets USA (31%), Belgium (28) and
China (25%).
Harvest Wrapping Up
Saskatchewan and Alberta each hit 97%
complete as of late October with Manitoba at
94%. The Peace is furthest behind at 89%, up 8%
on the week.
Futures Lower
All grain and oilseed futures are lower on the
week although the rate of the decline is easing
off. Trade in general has slowed as players are
collectively nervous about all the uncertainty in
the world. Two wars, an American election and
rising interest rates are not conducive to smooth
commerce.
Soybeans had the biggest drop while canola
had only minor losses. The canola crop is
essentially off and off-combine deliveries dried up.
Wheats are all lower with Minneapolis off 11
cents on the week. Black Sea exports remain
highly restricted but the world's buyers seem to be
coping.

Sell Feed Wheat
This past week, wheat for feed usage was trading
in the range of $300-$325/t delivered feedlot and
feedmill in Central and Southern Alberta. The
average elevator bid sourcing for export movement
for #1 CWRS 13.5% protein in Central and Southern
Alberta was in the range of $300-$310/t. In
Saskatchewan, the average elevator bid for #1
CWRS 13.5% protein was $287/t.
As the domestic feed market is premium to
offshore milling wheat values, farmers need to sell
feed wheat into domestic feed markets. Some
farmers in the major feeding regions of Western
Canada with higher quality wheat will sell into feed
channels and this will eventually result in lower feed
prices. But this will be a slow process and will take
some time.
High quality durum is also moving into feed
channels in volume. That’s another reason to be
mildly bullish durum wheat.
Sell 20% of feed wheat production, bringing total
sales to 40%.
Sell 20% of Feed Barley and Malting Barley
This past week, feedlots in Southern Alberta were
showing bids in the range of $295-$300/t delivered.
Central Alberta operations were showing bids at
$275-$290/t delivered.
Most feedlots have the bulk of their November
requirements covered. However, there is some open
demand for November but many feedlots are
sourcing for December and January. This is when
cattle on feed inventories in Western Canada are at
seasonal highs.
Some feedlots in Southern Alberta are using more
feed wheat than barley. Corn prices have been under
pressure and some feedlots are switching over to
imported U.S. corn. Sourcing 5,000-10,000 tonnes of
corn from one company is easier than arranging 500-
1,000 tonne barley deliveries from 10 to 20 farmers.
The malt barley market is hard to define due to the
lack of transparency from malting companies. China
buys barley on specifications known as “fair-
average-quality”. This is lower quality than Canadian
malt barley but higher than feed quality. Grain
companies sourcing for other export markets will only
make sales once they have the contracted volume
from farmers.
In France, feed barley was quoted at US$230/t fob
Rouen while malting barley was valued at US$265/t
fob. Canadian feed barley was quoted at US$240-
$250/t fob the West Coast. There are no firm offers
for malting barley but an indicative value is around
US$285-$290/t fob the West Coast.
Merchants are having a difficult time selling malting
barley on the world market because they can’t
source malting barley at prices competitive to
Europe. To be competitive with European offers,
grain companies have to buy malting barley at the
same price as feed barley in Western Canada. If you
can receive a premium for malt over feed quality, you
have to take it.
Sell 20% of feed and malting barley, bringing total
sales to 40%.


Grains and Oilseeds Supply/Demand
AgCanada - October 20, 2026
Production
Supply
Export
Domestic
Carry
Durum
Use
Out
2023
4,247
4,830
3,549
612
669
2024
6,380
7,054
5,821
722
512
2025f
7,305
7,825
5,825
878
1,102
2026f
6,417
7,524
5,300
874
1,350
Non-Durum
2023
29,167
34,382
21,771
8,002
4,609
2024
29,559
34,247
23,399
7,151
3,728
2025f
33,257
37,151
23,860
7,747
5,544
2026f
29,705
35,348
23,450
7,598
4,300
Barley
2013
8,905
9,731
3,064
5,515
1,152
2024
8,144
9,464
2,843
5,372
1,249
2025f
9,725
11,127
4,181
6,006
940
2026f
9,713
10,773
3,600
6,223
950
Oats
2023
2,643
3.933
2,365
898
670
2024
3,358
4,045
2,568
971
507
2025f
3,920
4,441
2,407
1,457
577
2026f
3,031
3,628
2,381
867
400
Rye
2023
358
466
198
177
91
2024
421
513
154
216
143
2025f
613
757
168
227
362
2026f
394
758
203
275
280
Canola
2023
19,464
21,602
6,679
11,698
3,225
2024
19,239
22,595
9,331
11,667
1,597
2025f
22,227
23,934
8,956
13,089
1,889
2026f
22,051
24,069
7,700
13,900
1,968
Flax
2023
273
502
211
127
164
2024
258
431
228
69
134
2025f
454
596
284
100
212
2026f
386
607
275
111
221
Note: Units in 1,000 tonnes
AgCanada's October Supply/Demand is the final
estimate for 2025 production, 5% lower than the 2025
crop but still the second biggest on record.
Durum's 2025 exports were the largest on record with
Algeria taking 27%, Morocco 18% and Italy 17%.
Production in 2026 was smaller but total supplies are
26% above average. Grades are somewhat below
average at 65% 1 and 2CWAD. Average protein is also
below average at 13.4%.